Contents
Saigon's CBD Branded Residences: Ritz-Carlton, Marriott and the Price of an Address
One Central, Grand Marina, The One Sài Gòn and The Prince Residence compared: price per m², yield, Metro Line 1 and the 50-year foreign ownership rules.
Central District 1 now has a very steep price ladder. At the top sits One Central Saigon – Vietnam's first Ritz-Carlton Residences, estimated by NAC at around USD 25,000 per square metre. Just below is the Marriott-branded Grand Marina Saigon, from USD 450,000. A few steps from Ben Thanh Market, the completed One Sài Gòn starts at USD 280,000. The higher you climb, the lower the rental yield: from 5.5–5.8% down to roughly 3%. Foreigners can own apartments for up to 50 years, renewable once, and no more than 30% of the units in any building.
Source: NAC listing data, Oct 2026; JLL Q2 2026; HCMC Urban Railway Management Board via Dan Tri (2025); Decree 95/2024
Earlier coverage of Vietnamese branded residences has mostly looked to the coast: Da Nang, Phu Quoc, Ho Tram. This piece turns back to the centre. The question isn't where to holiday, but what a District 1 address really costs – per square metre, in rental return, and in how long the law lets a foreigner hold it. All four projects here are scored in NAC's Residence Index rankings.
The District 1 Ladder: USD 3,500 to 25,000 per Square Metre
According to JLL's Q2 2026 report, high-end primary prices in Ho Chi Minh City averaged USD 5,335 per square metre, up 2.6% on the quarter and 5.1% on the year. Avison Young, quoted by Dan Tri in July 2026, puts central-city apartments at VND 91–153 million per square metre, with ultra-luxury projects approaching VND 470 million (about USD 17,940).
A seven-fold gap on the same block. One Central and The One Sài Gòn sit a roundabout apart, both facing Ben Thanh Market. Per NAC's listing data, The One Sài Gòn prices at USD 3,200–3,500 per square metre while One Central is estimated near USD 25,000. The gap isn't location – the locations are almost identical – it's the operating brand, the age of the building and its status as a landmark.
One Central Saigon: The First Ritz-Carlton, the Lowest Yield
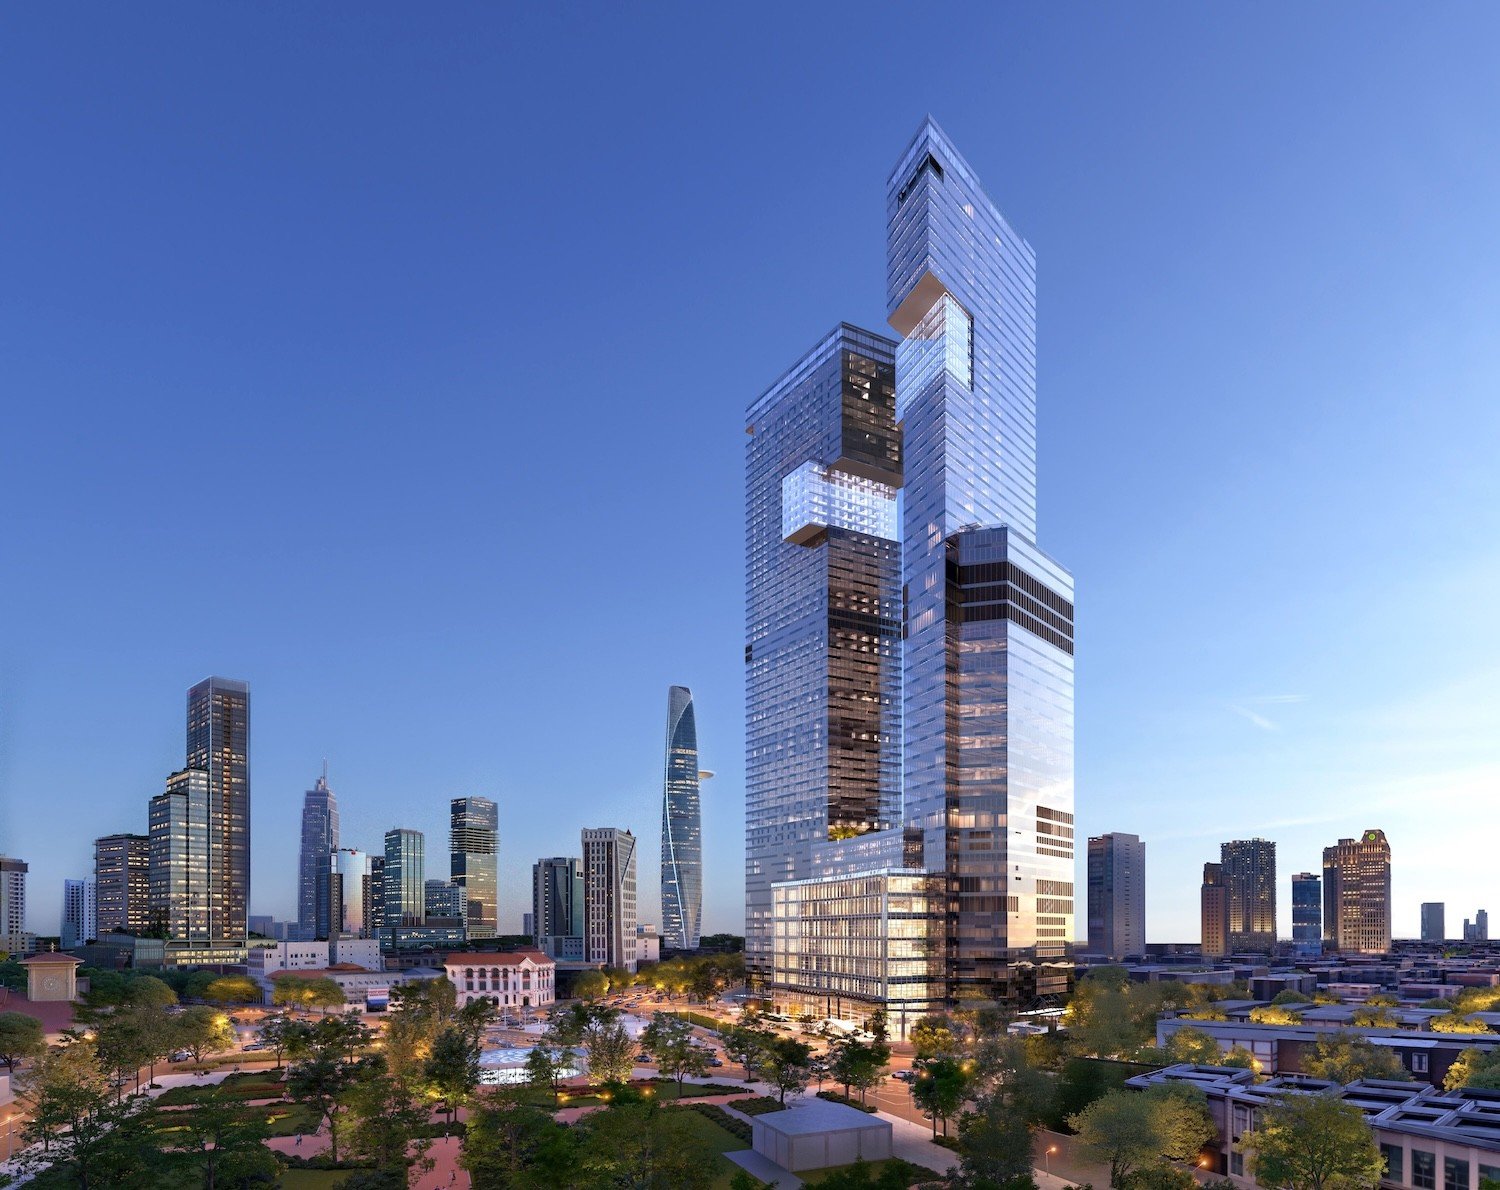
One Central Saigon, The Ritz-Carlton Residences is Masterise Homes' project on the Ben Thanh roundabout, designed by Arquitectonica. Per NAC's listing data, the 46-storey East tower holds about 350 branded residences of one to three bedrooms, roughly 90–200 m², with handover targeted for 2027. NAC records an entry price of USD 2.25 million, a gross yield of around 3% and a NAC score of 82/100.
The gap isn't location – the locations are almost identical – it's the operating brand and the status of a landmark.
This is an asset for preserving value and status, not for living off cash flow. NAC's listing is candid about the limits: a 50-year ownership framework for foreigners, no residency programme, a thin secondary market and a construction history that once stalled. The developer has not released an official price list, so every figure beyond developer guidance is a NAC estimate.
Grand Marina Saigon: Marriott on the Saigon River
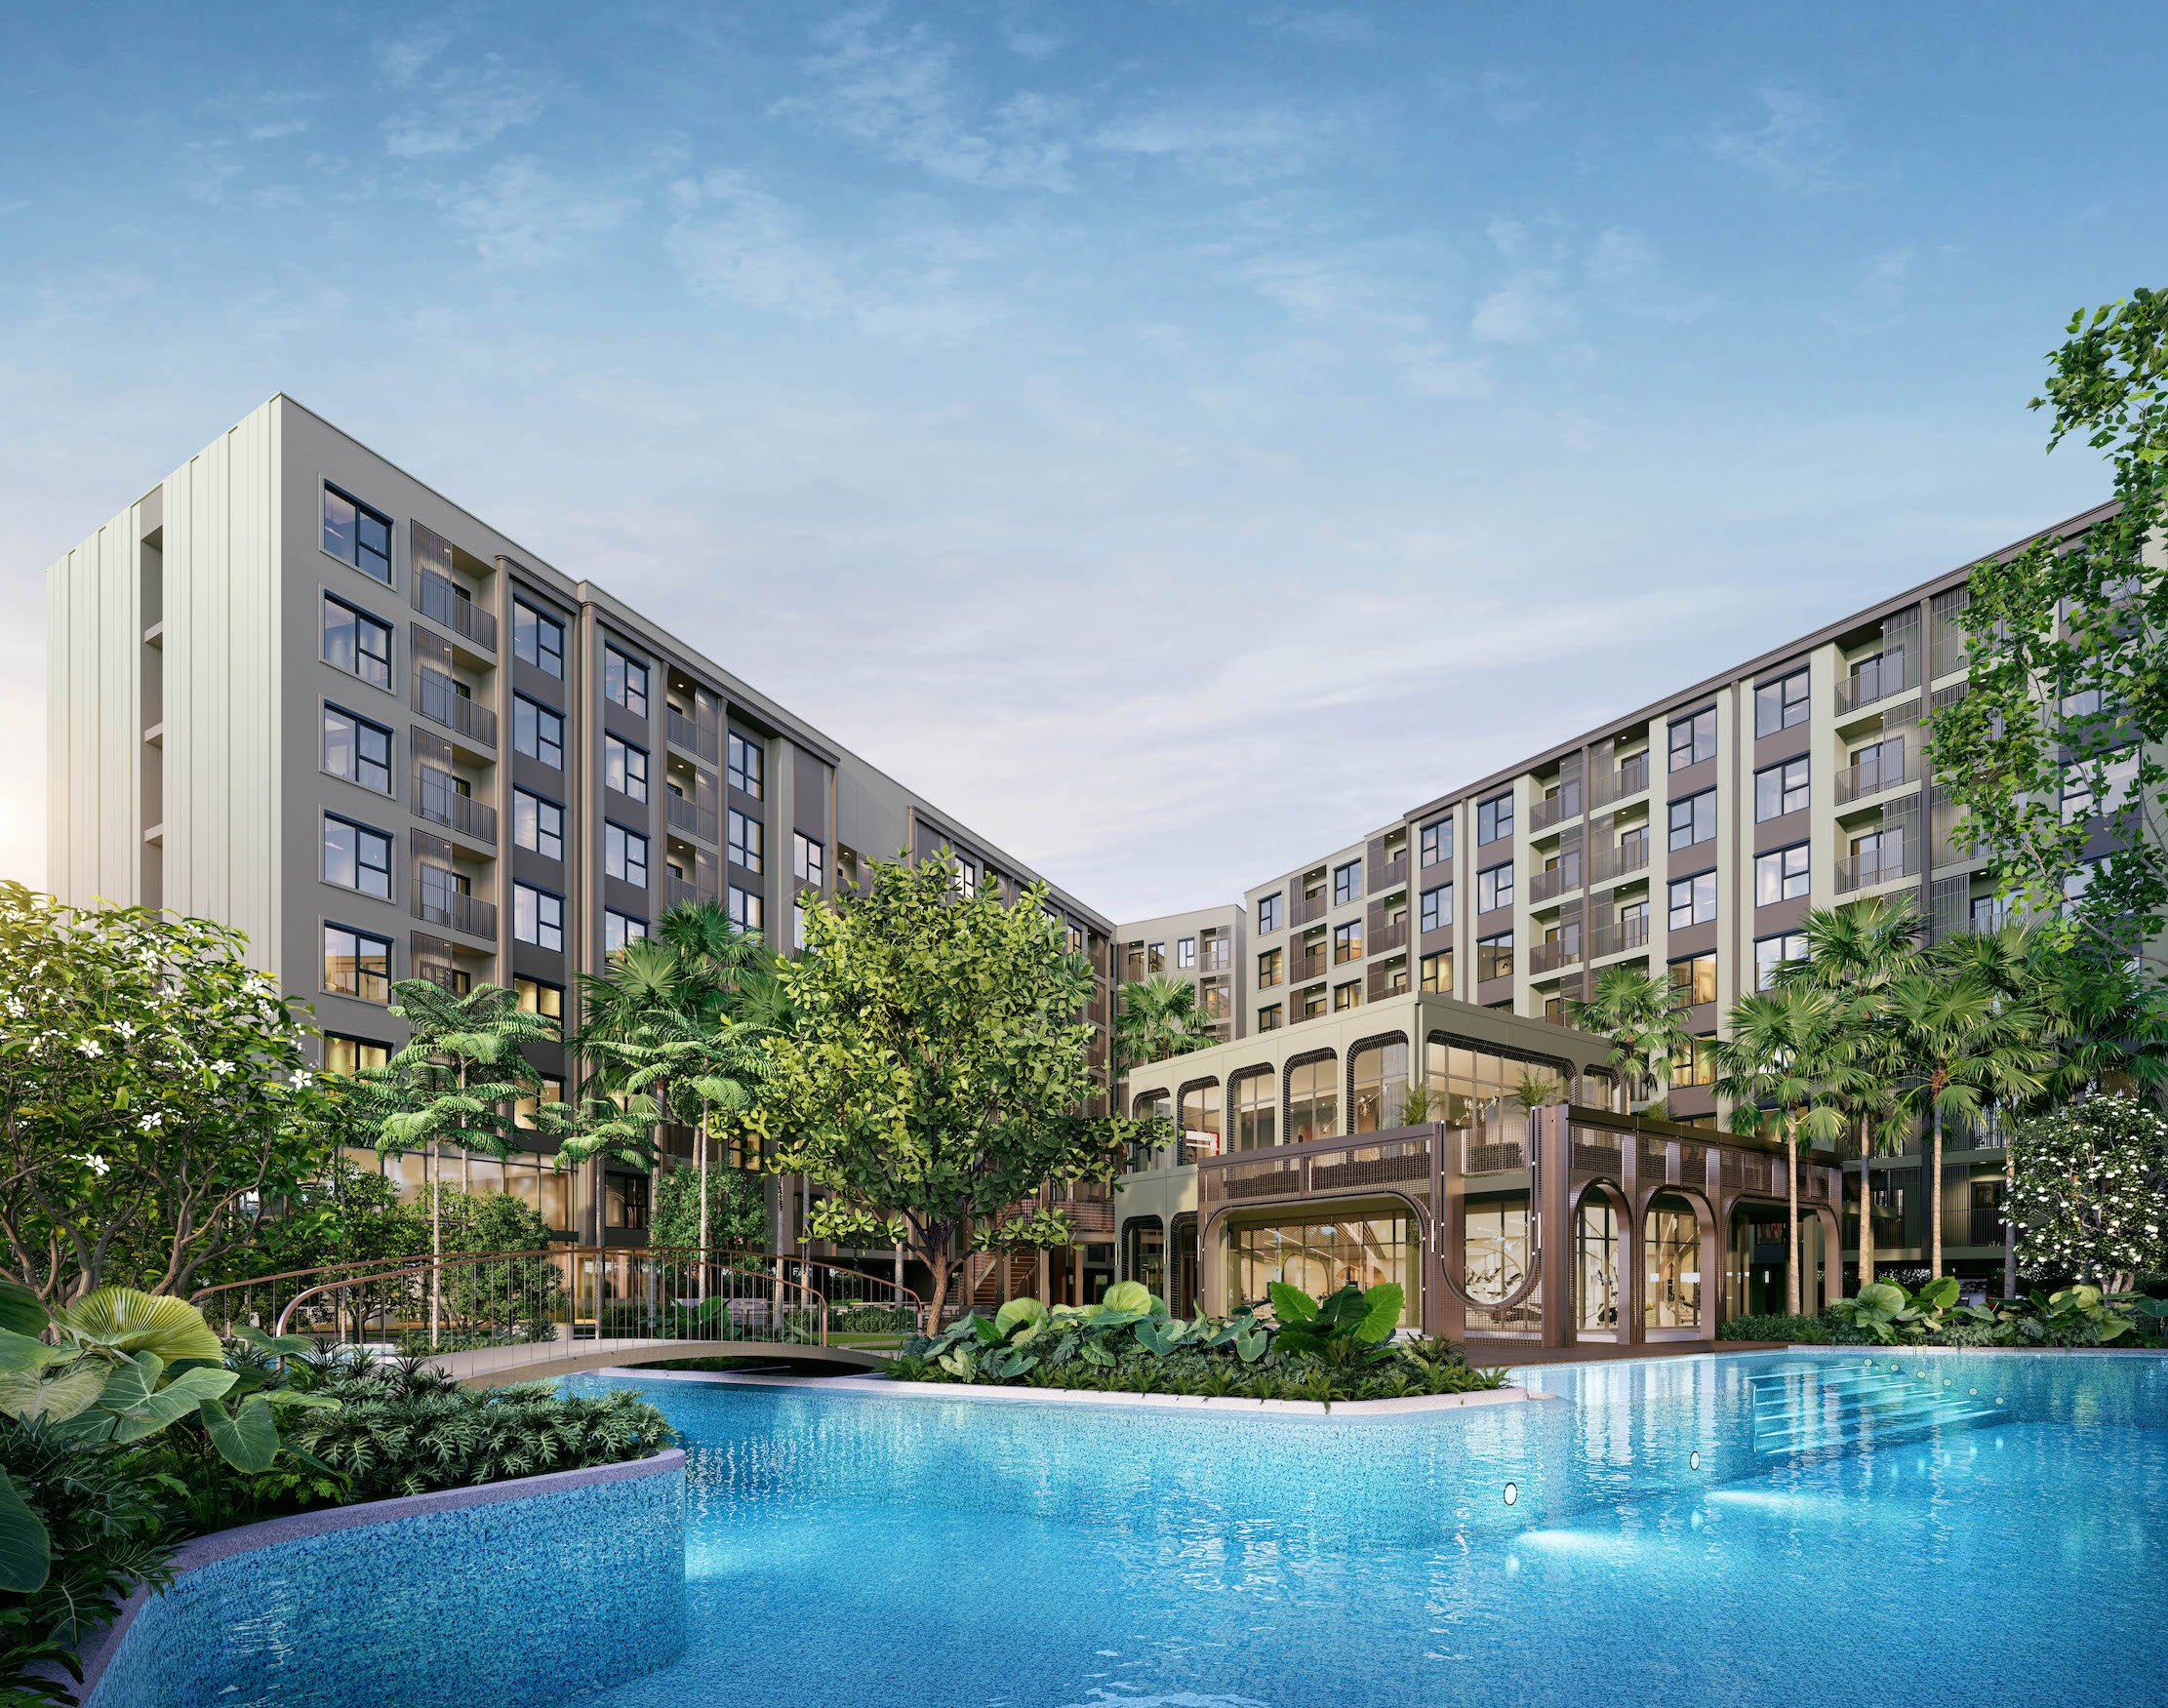
Also by Masterise Homes, Grand Marina Saigon on the Ba Son site is presented as the world's largest Marriott and JW Marriott branded-residence complex, stretched along about 500 metres of riverfront. Per NAC's listing data it starts at USD 450,000, with a 5.8% gross yield and a NAC score of 81/100, and phased delivery during 2026. Units are handed over fitted to Marriott's interior standards, and owners can join an operator-managed rental programme.
Compared with One Central, Grand Marina trades a little scarcity for clearly better cash flow. It is also the project NAC treats as the benchmark for Vietnam's branded segment.
The One Sài Gòn and The Prince Residence: Two Cheaper Doors In
The One Sài Gòn opposite Ben Thanh Market is a completed, operating 22-storey tower by Capella Holdings. Per NAC's listing data it has 126 units from 53 to 135 m², prices from USD 280,000, a 5.5% gross yield and a NAC score of 78/100, about five minutes' walk from Ben Thanh metro station.
No river, no hotel brand – but the same yield as The One Sài Gòn for about half the capital.
To see what District 1 really costs, set it against an option just outside the core. The Prince Residence in Phu Nhuan, by Novaland, was delivered in 2015 and has 327 units. Per NAC's listing data, a one-bedroom of about 50 m² starts at USD 144,000, yields 5.5% and scores 80/100, about five minutes from Tan Son Nhat airport. No river, no hotel brand – but the same yield as The One Sài Gòn for about half the capital.
Metro Line 1 and Ownership Law: The Two Background Variables
Metro Line 1, Ben Thanh–Suoi Tien, opened on 22 December 2024. According to the Urban Railway Management Board, reported by Dan Tri in December 2025, the 19.7 km, 14-station line carried about 18.95 million rides by 15 December 2025, averaging around 52,000 a day. For the centre, the line's value is in tying District 1 to the eastern suburbs, which widens the pool of potential tenants. Ben Thanh station sits between One Central and The One Sài Gòn.
On the law, Article 20.2.c of the 2023 Housing Law lets a foreign individual own housing for up to 50 years from the date the certificate is issued, renewable once for another 50. Decree 95/2024/ND-CP caps foreign ownership at 30% of the apartments in each building, as Vietnam Law Magazine explains. In central projects the 30% cap is practical, not theoretical: where foreign demand is strong, the foreign quota can sell out before the rest of the inventory. Vietnamese citizens are not subject to these limits.
A practical strategy for Vietnamese investors
Separate value preservation from cash flow. One Central serves the first goal, Grand Marina and The One Sài Gòn balance the two, and The Prince Residence leans towards the second.
Check the foreign quota before paying a deposit. If the buyer is an overseas Vietnamese with foreign citizenship, or a relative without Vietnamese nationality, ask the developer how much of the 30% quota remains.
Read the construction timeline carefully. A completed building earns from day one; one still under construction, like One Central, carries timing risk, especially with an interrupted build history.
Put Saigon inside a wider portfolio. A central apartment can be the domestic leg of a portfolio, paired with an asset abroad that carries residence rights.
Explore on NAC
 ×
 One Central Saigon🇻🇳 Ho Chi Minh City · from $2.3MYield 3.0%
 ×NobuNobu Residences Da Nang🇻🇳 Da Nang · from $360KYield 6.0%×Grand Marina Saigon🇻🇳 Ho Chi Minh City · from $450KYield 5.8%×CapellaThe One Sài Gòn🇻🇳 Vietnam · from $280KYield 5.5%×NovalandThe Prince Residence🇻🇳 Ho Chi Minh City · from $144KYield 5.5%
See also: All Vietnam projects on the Property Hub · NAC's full Property Hub · Compare residence programmes
Frequently asked questions
Can foreigners buy an apartment in District 1?
Yes. Under the 2023 Housing Law and Decree 95/2024, a foreign individual legally permitted to enter Vietnam can own an apartment in a commercial project for up to 50 years, renewable once, within the 30%-per-building cap.
Why is One Central's yield so low?
Its price per square metre is several times the market average, while rents don't rise in proportion. Per NAC's listing data the gross yield is about 3%, so it's a value-preservation asset rather than a cash-flow one.
Does Metro Line 1 lift central apartment prices?
It widens the tenant pool and improves access, but prices depend on many other factors. There is no public data isolating the metro's effect on District 1 prices.
NAC strategic insight
Central Saigon doesn't have one price; it has a ladder. On the same Ben Thanh roundabout you can pay USD 3,500 or USD 25,000 per square metre, and the yield moves the opposite way. What matters is knowing what you are paying for: the location, the brand, or a story about the future.
NAC scores every project on one yardstick so Vietnamese families can compare fairly across central apartments, beachfront residences and assets abroad. If you'd like to see which fits your goals, book a consultation with NAC.
Sources